الذكاء الاصطناعي ومراكز البيانات
توسّع الذكاء الاصطناعي في المملكة
يرسم التقرير مسار بناء مراكز البيانات وقدرات حوسبة الذكاء الاصطناعي في المملكة: القاعدة التشغيلية، وخطط المجمّعات، وشراكات التقنية والحوسبة السحابية حولها، مع الفصل بين تصنيفات المجمّعات ومراحلها وعقودها حتى لا يُحسب الإعلان الواحد مرتين. رقم الغلاف 8.4 GW من القدرة المُعلَنة، مقرَّبًا من 8.447 GW: القاعدة التشغيلية الوطنية 467 MW مع خطط مجمّعات السعد وأوكساجون وهيكساجون، ويصفه التقرير بأنه تغطية منتقاة تجمع مراحل مختلفة لا قدرة ذكاء اصطناعي عاملة أو مُلتزَمًا بها. الأرقام كما أُعِدّت في 21 سبتمبر 2026، ويحتفظ كل سجل بتاريخ مصدره.
- أُعِدّ في 21 سبتمبر 2026
- عدد الصفحات: 21
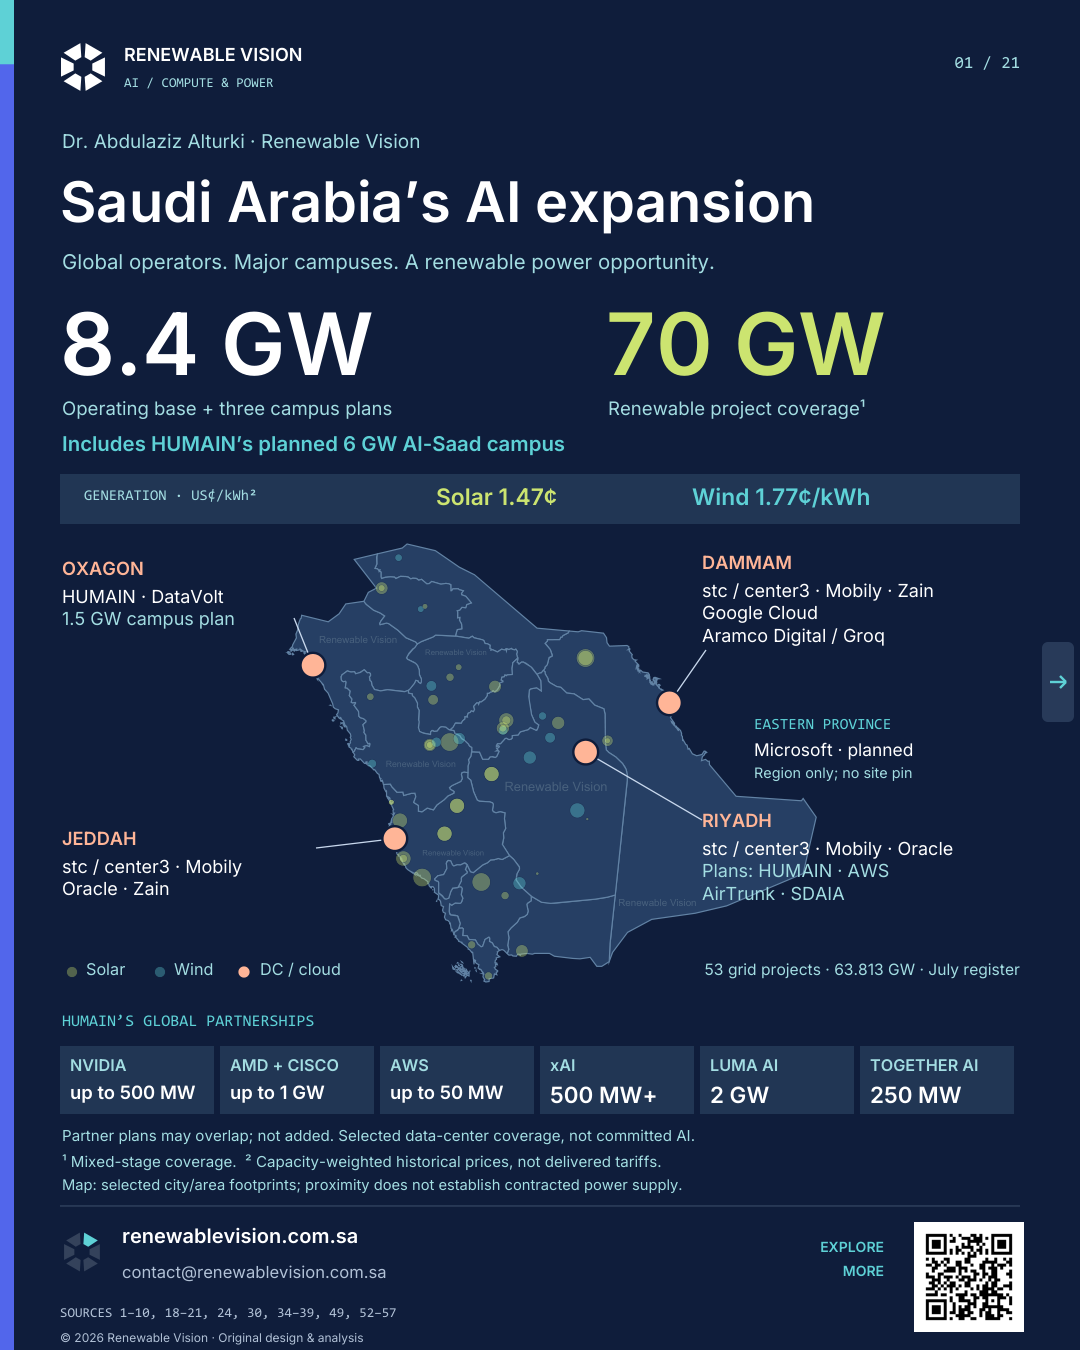
ما يغطيه التقرير
8.4 GW of reported capacity across Saudi Arabia’s operating data-center base and three major campus plans.
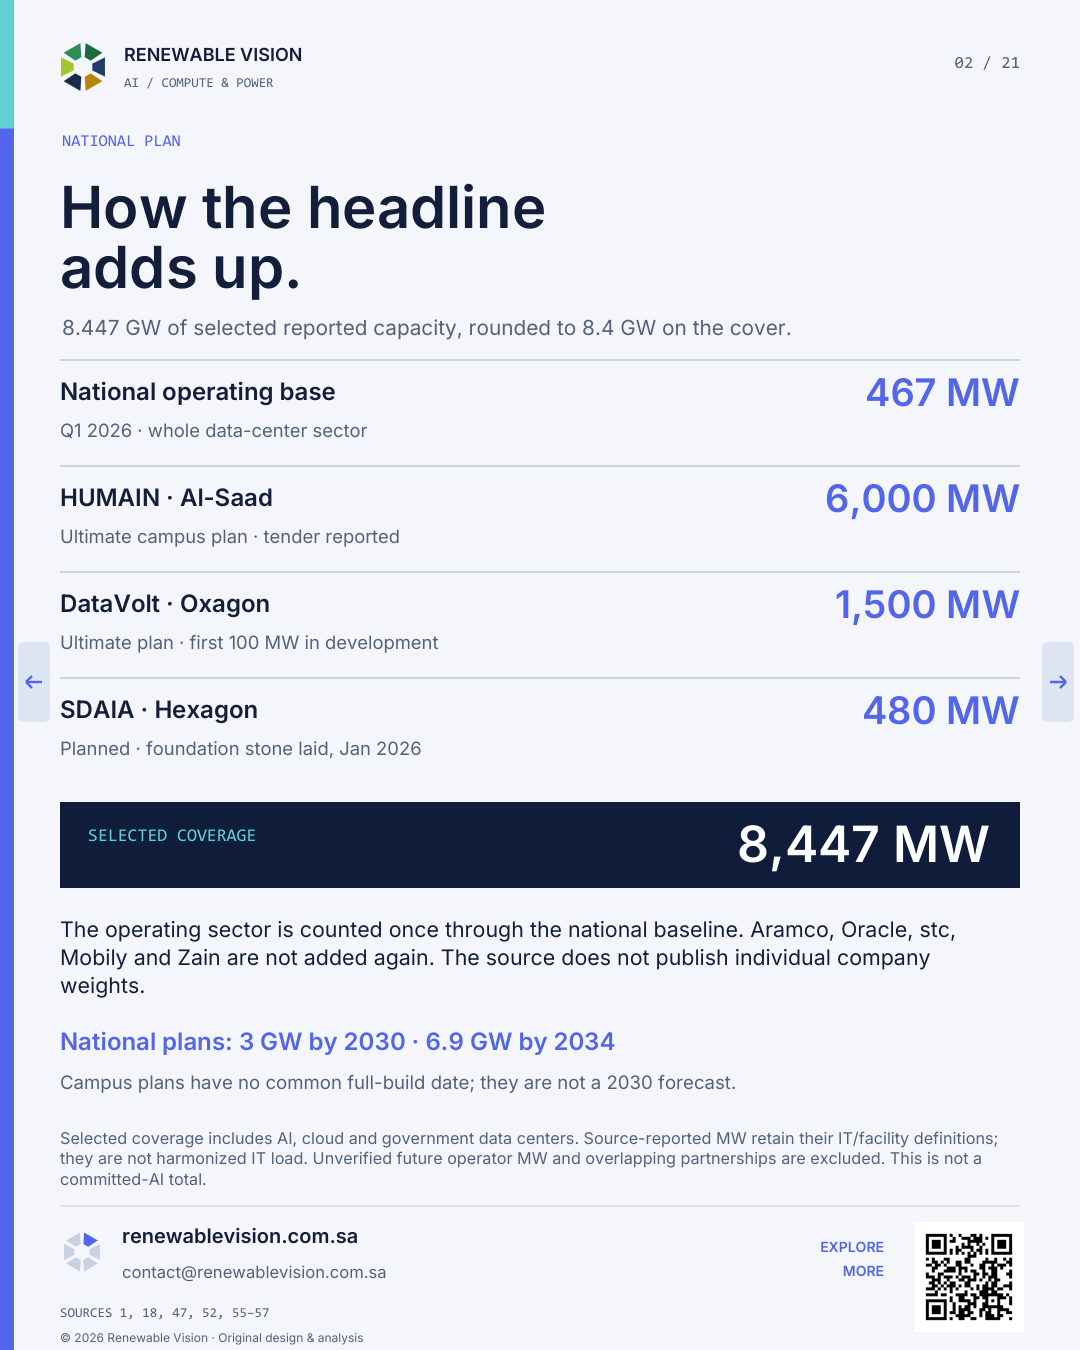
The calculation: 467 MW in the national operating baseline, HUMAIN’s planned 6 GW Al-Saad campus, DataVolt’s 1.5 GW Oxagon campus and SDAIA’s 480 MW Hexagon project. This is selected mixed-stage coverage, not 8.4 GW operating or committed AI capacity.
NVIDIA. AMD and Cisco. AWS. xAI. Luma AI. Together AI. These partnerships show the breadth of the compute ecosystem taking shape. Their announced capacities can overlap with campus plans, so they are not added again.
Saudi Arabia’s AI opportunity extends from the power system to the cloud.
The national data-center plan reaches 3 GW by 2030 and 6.9 GW by 2034. Alongside it are major campus ambitions: HUMAIN’s planned 6 GW Al-Saad campus and DataVolt’s 1.5 GW Oxagon campus.
But the market is wider than those two projects. Aramco Digital, Oracle, stc/center3, Mobily and Zain are part of the infrastructure and service base, alongside HUMAIN’s technology and cloud partnerships.
This Renewable Vision report maps who is involved, what is operating, what is planned and where the energy opportunity lies. It also distinguishes campus ratings from phases and contracts, so overlapping announcements are not counted twice.
The power context matters: the earlier Renewable Vision register covers about 70 GW of renewable projects across stages. Its priced sample has capacity-weighted historical benchmarks of 1.47 US cents/kWh for solar and 1.77 for wind. These are generation benchmarks, not round-the-clock delivered tariffs.
Competitive AI exports will depend on turning that starting position into dependable power, efficient cooling, advanced compute and customers.
ما تعنيه الأرقام
مقتبس من ملاحظات التقرير نفسه عن النطاق والتعريفات، بالصياغة التي نُشرت بها.
- 8.4 GW is Renewable Vision's selected mixed-stage coverage, rounded from 8.447 GW: the 467 MW whole-sector operating baseline plus Al-Saad 6,000 MW, Oxagon 1,500 MW and SDAIA Hexagon 480 MW. This broad indicator retains published rating conventions; it is not harmonized IT capacity, an exhaustive pipeline, committed AI or a common-year forecast.
- Existing companies are represented through the national operating baseline, whose publisher does not disclose company-by-company weights. Their entire future plans cannot be assumed included. Undisclosed or unresolved future operator MW are not added as estimates.
- 467 MW: official operational data-center capacity in Q1 2026, reiterated by MCIT in July. Includes more than AI; IT/facility boundary is not fully specified in the release.
- 3 GW by 2030 and 6.9 GW by 2034: MCIT national plans for the whole data-center sector. They are not a sum of corporate announcements.
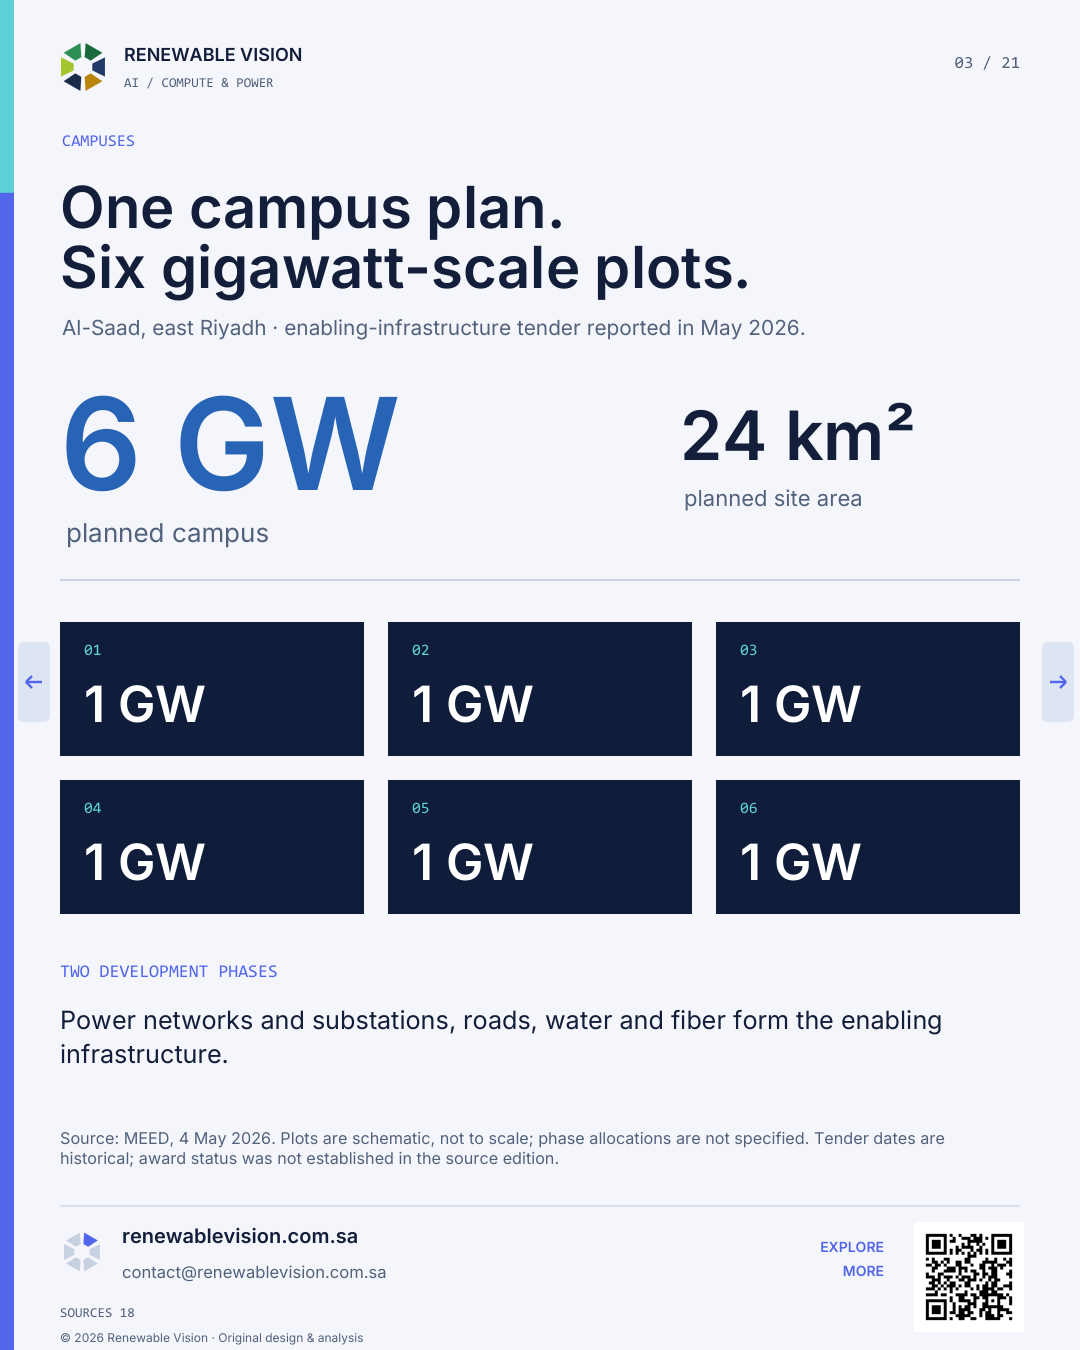
- Al-Saad 6 GW and Oxagon 1.5 GW: distinct ultimate campus plans without a common complete-build deadline. Hexagon 480 MW: a separate SDAIA government-campus project with foundation stone laid in January 2026. These three plans are counted once; phases and partnerships are excluded from additional capacity.
- stc/center3: 250 MW reported total and 202 MW live at end-2025; the latter is contained in the former.
- Mobily: 39 MW development program, containing 13 MW commissioned in 2025. These are not the entire technical/commercial portfolio; the broader >122 MW disclosure has a different boundary.
- Aramco Digital/Groq: inference partnership and live Dammam service. Oracle: Riyadh and Jeddah public cloud regions. Zain: selected Jeddah/Dammam site disclosures and a September DataVolt MoU. Comparable MW are not disclosed in the reviewed primary sources and remain null rather than zero.
- HUMAIN/MIS: 250 MW signed planned scope, disclosed 20 September 2026; execution via later work orders. The earlier 50 MW is replaced, not added.
المصادر
يحتوي ملف PDF كذلك على صفحة مصادره الخاصة.
- NEOM / DataVolt. Oxagon AI campus construction. 31 Aug 2026
- AMD / Cisco / HUMAIN. Systems live; 250 MW next phase; 1 GW target. 31 Aug 2026
- AWS. Cloud region December 2026; AI Zone up to 50 MW by 2028. LEAP 2026
- AWS / HUMAIN. AI Zone location: Riyadh. 19 Nov 2025
- Microsoft. Saudi Arabia East: November 2026 availability. Aug 2026
- Oracle. Riyadh and Jeddah cloud regions. Current service page
- Google Cloud. Dammam cloud region open. 15 Nov 2023
- NVIDIA / HUMAIN. Up to 500 MW projected over five years. 13 May 2025
- KAPSARC. Renewable Energy Projects Dashboard. July 2026 snapshot; checked 11 Sep
- SPPC / Principal Buyer. Renewable projects and prices. Register checked 11 Sep 2026
- IEA. Key Questions on Energy and AI. 2026
- European Commission JRC. PVGIS: hourly radiation and PV estimates. PVGIS 5.3 SARAH3; July 2019–2023 sample
- center3 / PDC. Data-center power planning partnership. 31 Aug 2026; page dated 1 Sep
- DataVolt / Zain KSA. Saudi data-center portfolio MoU. 1 Sep 2026
- geoBoundaries / OSM contributors. Saudi province boundaries; ODbL 1.0. Generalized map; indicative locations
- Acwa. NEOM Green Hydrogen project. 3.9 GW project power; dedicated industrial system
- US Department of Energy / FEMP. Data-center cooling, PUE and WUE. Technical guidance; checked 12 Sep 2026
- MEED. Al-Saad: 6 GW campus infrastructure tender. 4 May 2026
- MEED. AirTrunk–HUMAIN: 250 MW Riyadh bids. 27 Apr 2026
- Together AI / Business Wire. 250 MW Saudi partnership with HUMAIN. 31 Aug 2026
- Luma AI. Project Halo: planned 2 GW compute supercluster. 19 Nov 2025
- Qualcomm. HUMAIN: 200 MW infrastructure deployment plan. 27 Oct 2025
- Qualcomm / Adobe. Adobe AI data-captioning workloads on HUMAIN. 31 Aug 2026
- Groq. Dammam deployment; official HUMAIN inference provider. 27 May 2025
- xAI. Grok Goes Global: HUMAIN infrastructure framework. 19 Nov 2025
- stc / Saudi Exchange. HUMAIN MoU: 1 GW ambition, initial up to 250 MW. 18 Dec 2025
- MIS / Saudi Exchange. HUMAIN project scope expanded from 50 to 250 MW. 26 Aug 2026
- MIS / Saudi Exchange. Correction: authorization date was 25 August 2026. 26 Aug 2026
- MEED. HUMAIN–DataVolt start Oxagon construction. 1 Sep 2026
- Blackstone / AirTrunk. HUMAIN partnership to develop Saudi data centers. 28 Oct 2025
- MEED. Taranis–Emaar Executive: 40–50 MW facilities planned. 29 Apr 2026
- MEED. Zoom launches Saudi data center at center3. 9 Jun 2026
- Fast Company Middle East. CEO interview: national expansion ambition. 7 Nov 2025
- stc. Sustainability Report 2025: facility list and capacity, p.117. 2025 reporting year
- Mobily. Annual Report 2025: two new centers, 13 MW combined. 2025 reporting year
- Mobily. Business Solutions Q1 2024: named facilities, p.144. Q1 2024
- Mobily. Colocation service: four-city footprint. Checked 12 Sep 2026
- Zain KSA. Annual Report 2025: data-center strategy, pp.60–61. 2025 reporting year
- Zain KSA. Sustainability Report 2024: site reporting and glossary. 2024 reporting year; pp.59–60, 131–132
- center3. Colocation service: 25 centers across three countries. Checked 12 Sep 2026
- stc. Year-End 2025 release: center3–HUMAIN JV partnership. Year-end 2025 results release
- Mobily. FastConnect: Jeddah Fayha and center3 Janadriah. Checked 12 Sep 2026
- Mobily. Annual Report 2025: Khurais, portfolio and 39 MW program. 2025 reporting year; pp.20, 96–97, 102–103
- Acwa. The Red Sea: commercial operation. 6 Sep 2026; 340 MWac / 1,227 MWh
- Red Sea Global. AMAALA utility concession. 11 Sep 2023; 700 MWh design
- MEED. ENOWA Gayal and Shiqri tenders. 24 Jul 2024; current award unverified
- Saudi Press Agency / MCIT. LEAP East: 467 MW operating; 3 GW by 2030; 6.9 GW by 2034. 8 Jul 2026; checked 21 Sep
- MIS / Saudi Exchange. HUMAIN agreement signed 19 September; 250 MW scope; execution through work orders. 20 Sep 2026; checked 21 Sep
- HUMAIN / PR Newswire. xAI framework: planned flagship of 500 MW+. 19 Nov 2025; checked 21 Sep 2026
- HUMAIN / Cohere; issuer release via Zawya. At least 50 MW dedicated compute; Q4 2027 expected. 9 Jul 2026; checked 21 Sep
- National Infrastructure Fund / HUMAIN. Non-binding financing framework for up to 250 MW. 21 Jan 2026; checked 21 Sep
- Saudi Press Agency. Operational data-center capacity: 467 MW in Q1 2026. 2 May 2026; checked 21 Sep
- Aramco Digital / Groq. Aramco Digital and Groq inference partnership. 12 Sep 2024; checked 21 Sep 2026
- Oracle. Saudi cloud and AI investment: USD 14 billion over ten years. 13 May 2025; checked 21 Sep 2026
- Saudi Press Agency / SDAIA. Hexagon data center: foundation stone laid, 480 MW planned. 1 Jan 2026; checked 21 Sep
- Saudi National Portal / SPA / MCIT. LEAP East: 467 MW operating, national 3 GW 2030 and 6.9 GW 2034 plans. 8 Jul 2026; checked 21 Sep
- Saudi National Portal / SPA. Saudi data-center operational capacity in Q1 2026. 2026; checked 21 Sep
معاينة
الصفحات المعروضة: 3 من 21
الحصول على التقرير
توسّع الذكاء الاصطناعي في المملكة
احصل على ملف PDF مجانًا مع العضوية
ملف PDF وملفات البيانات متاحة مجانًا للأعضاء. تستغرق العضوية دقيقة: تحقّق من بريد إلكتروني أو رقم جوال مرة واحدة، ليُفتح التنزيل مع لوحات البيانات وتصدير CSV.
أنشئ حسابًا مجانيًا ويبدأ التنزيل فور دخولك، ثم تعود إلى هذا التقرير.
لست مستعدًا للانضمام بعد؟
الموجز الأسبوعي
الطاقة المتجددة في المملكة أسبوعيًا: تغيّرات مراحل المشاريع والمناقصات ومواعيد التشغيل التجاري. رسالة واحدة يوم الأحد.
إذا تابعت بأحد هذه الحسابات، فأنت توافق على شروط الاستخدام، بما فيها الترخيص وأحكام العضوية، وعلى سياسة الخصوصية.
نستخدم بياناتك لنتيح لك الوصول، ولنرسل إليك الموجز الأسبوعي أو التنبيهات التي تختارها إن طلبت ذلك. سياسة الخصوصية
الأرقام كما صدرت في 21 سبتمبر 2026؛ وقد تختلف لوحات البيانات الحية. افتح لوحة البيانات الحية