الطاقة المتجددة
الطاقة المتجددة وتخزين البطاريات في المملكة: الدليل الكامل
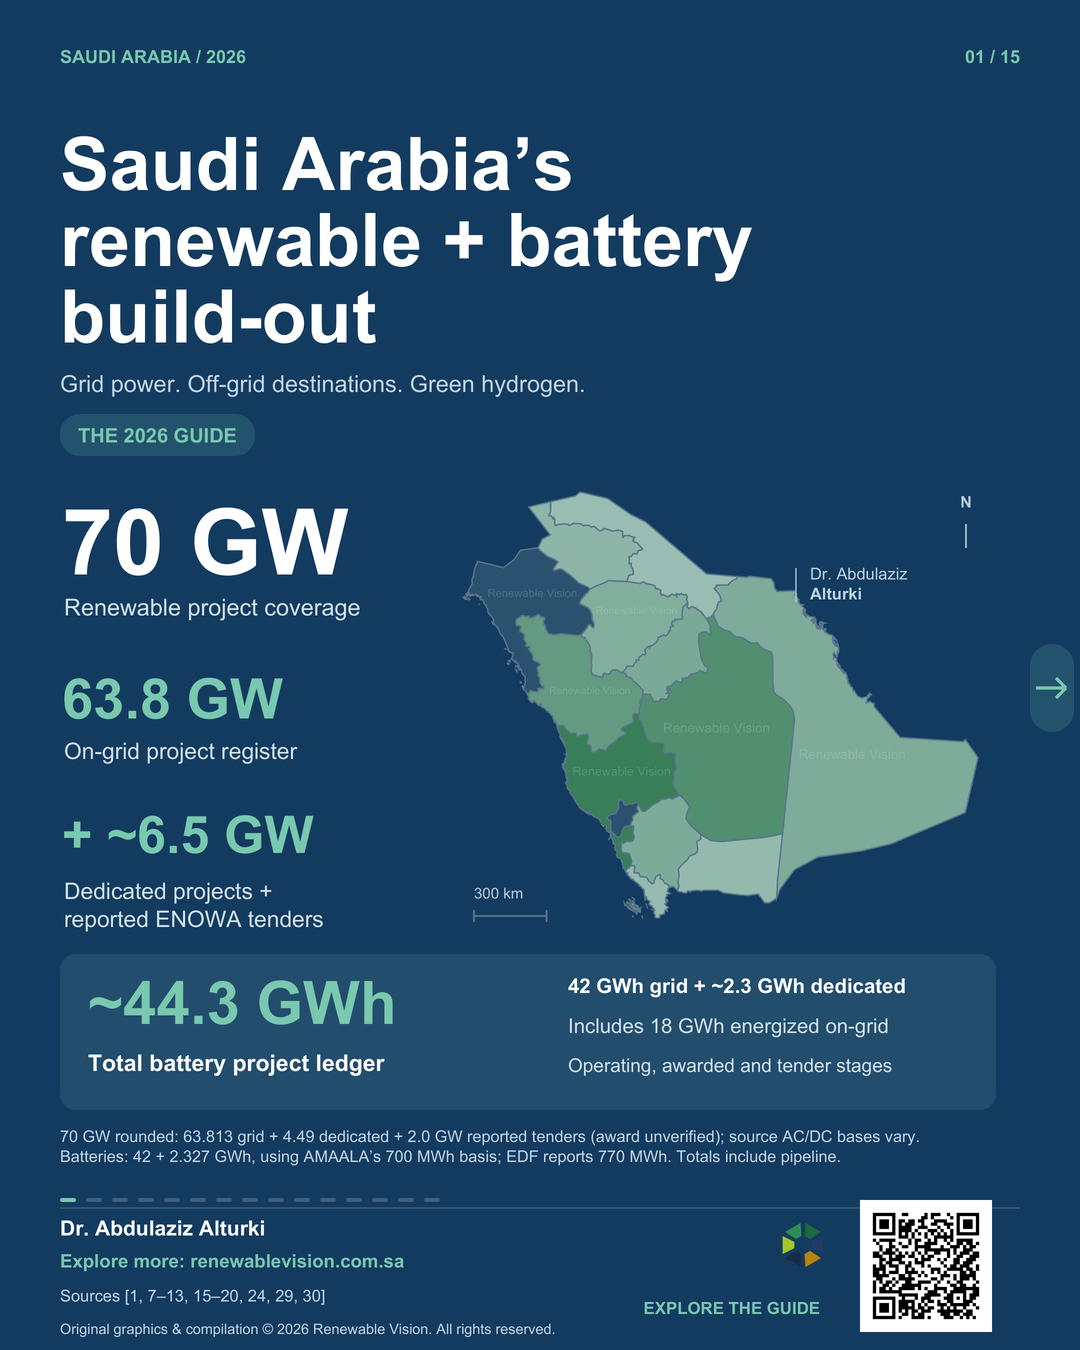
دليل واحد يغطي الطاقة المتجددة وتخزين البطاريات والأنظمة المخصصة خارج الشبكة والهيدروجين في المملكة، مع تحديد الأصول العاملة ومراحل المسار على كل خريطة. يغطي نحو 70 GW من مشاريع الطاقة المتجددة، و70.303 GW قبل التقريب: سجل الشبكة لدى كابسارك 63.813 GW، و4.49 GW في نيوم للهيدروجين الأخضر والبحر الأحمر وأمالا، و2 GW من مناقصات إينوا المُبلَّغ عنها منفصلةً والتي لم يُتحقَّق من إرسائها، إضافة إلى 44.3 GWh من مشاريع البطاريات. الأسعار متوسطات مرجّحة بالقدرة على المشاريع المُسعَّرة وحدها: 1.47 US cents/kWh للطاقة الشمسية و1.77 لطاقة الرياح، وهي مؤشرات توليد لا تعرفة كهرباء مُسلَّمة على مدار الساعة. مراجعة المصادر العامة بتاريخ 11 سبتمبر 2026، مع تحققات القدرة والتكلفة في 12 سبتمبر.
- أُعِدّ في 12 سبتمبر 2026
- عدد الصفحات: 15
ما يغطيه التقرير
Saudi Arabia's renewable expansion is becoming a story about entire energy systems.
Solar and wind projects supply the grid. Batteries shift energy across the day. Off-grid destinations combine electricity, water and cooling. Hydrogen projects connect renewable power to industry and exports.
This illustrated guide covers approximately 70 GW of renewable projects and 44.3 GWh of battery projects, with operating assets and pipeline stages identified.
The renewable total starts with KAPSARC’s 63.8 GW grid register, adds 4.49 GW at NEOM Green Hydrogen, The Red Sea and AMAALA, and includes 2 GW of separately reported ENOWA tenders whose current awards remain unverified. The underlying total is 70.303 GW, rounded to 70 GW on the cover.
The battery ledger combines 42 GWh of grid projects with approximately 2.3 GWh of dedicated systems. Of the grid total, 18 GWh was energized by June 2026; the balance includes awarded and procurement-stage projects.
Inside the guide:
• Solar and wind maps with 38 reported project prices: capacity-weighted averages of 1.47 and 1.77 US cents/kWh.
• Named battery projects, their reported capacities and procurement stages.
• Saudi battery equipment/EPC auction costs, alongside a separately labeled modeled LCOS benchmark.
• Dedicated renewable systems and the two ENOWA tender records together on one map.
• Selected procurement cycles compared separately from actual renewable additions, including China.
One distinction matters throughout: a tender is not an operating plant, and a generation price is not the cost of electricity delivered around the clock.
The main public-source review is dated 11 September 2026, with targeted capacity and cost checks on 12 September. Detailed source dates, capacity definitions and links are included in the guide. The dedicated battery total uses AMAALA’s 700 MWh basis; EDF reports 770 MWh for the same asset. NGHC’s 400 MWh system rating is kept separate from its supplier’s 600 MWh DC quantity.
Which interface deserves the next closer look: storage, water, hydrogen or industrial demand?
ما تعنيه الأرقام
مقتبس من ملاحظات التقرير نفسه عن النطاق والتعريفات، بالصياغة التي نُشرت بها.
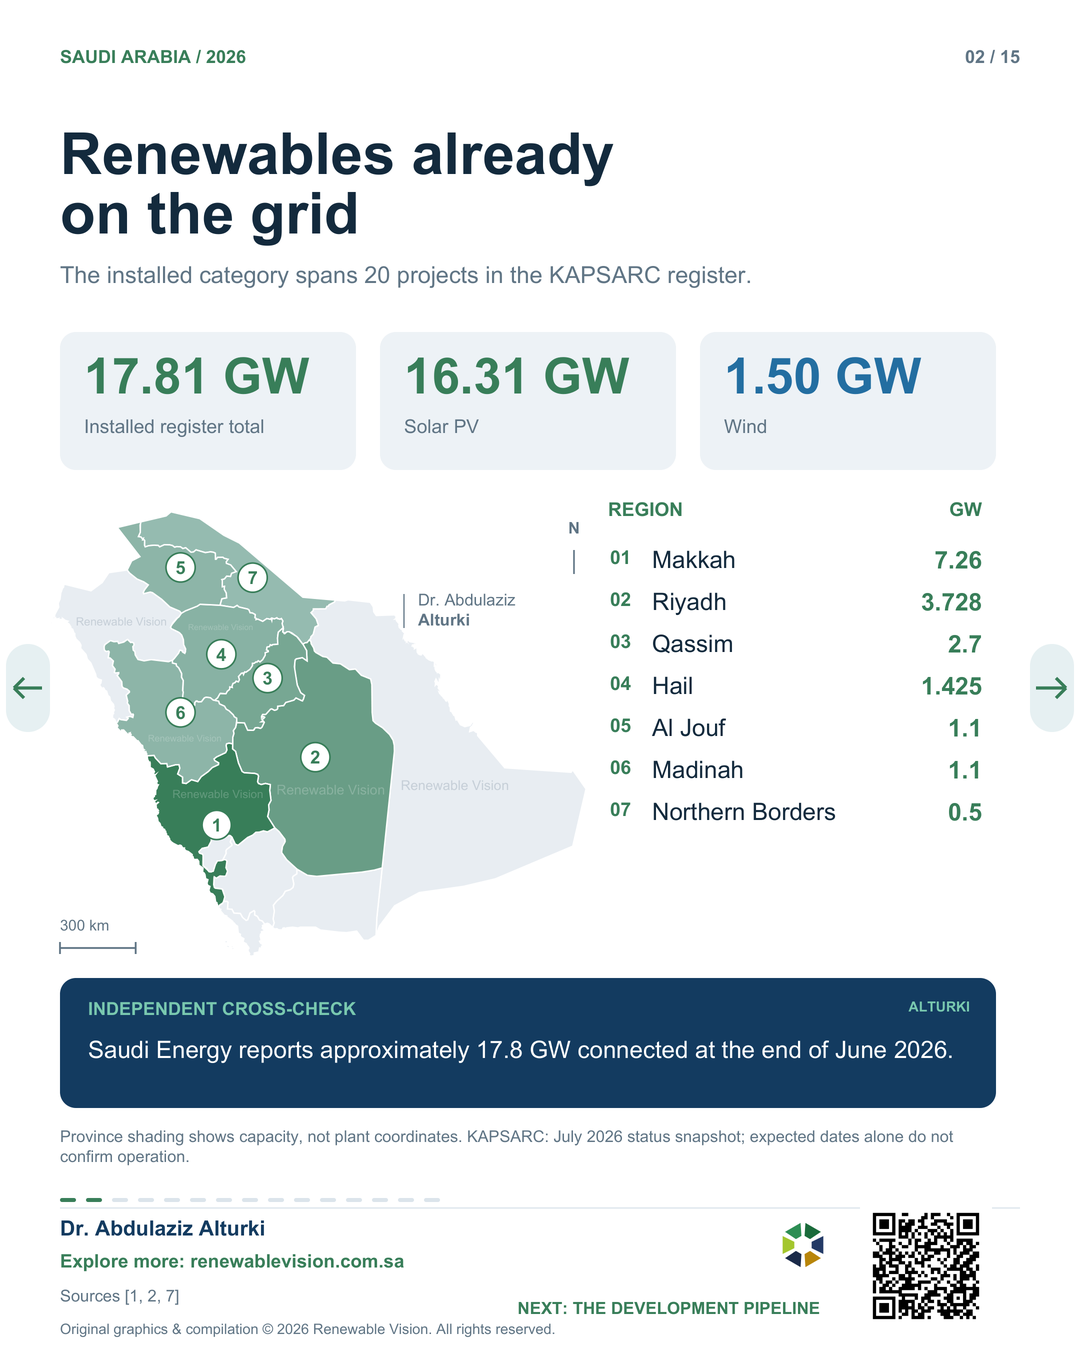
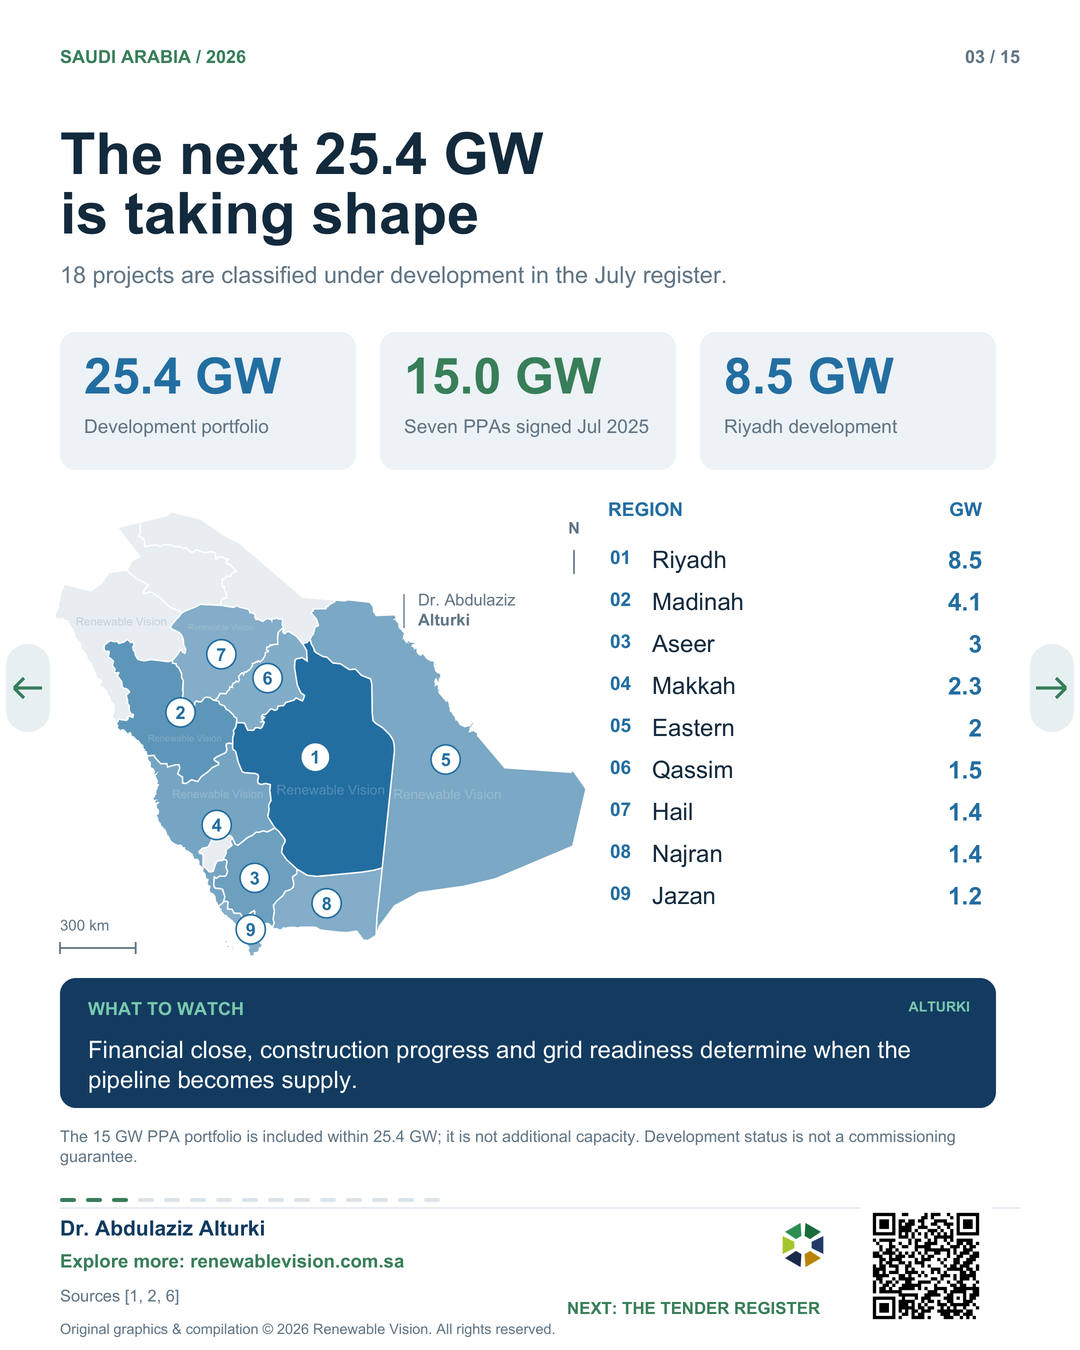
- Grid renewables: 53 KAPSARC records, 63.813 GW in the July 2026 snapshot. Installed: 17.813 GW; development: 25.4 GW; tendered: 20.6 GW. This is a project register including pipeline, not a total of operating generation. All 38 SPPC awarded project names/capacities were reconciled. SPPC status filters lag five KAPSARC records; Saudi Energy independently reports about 17.8 GW connected by June 2026.
- Renewable tenders: all 15 tendered register records are listed. The six Round 7 projects total 5.3 GW and are already included. The other nine total 15.3 GW; no unverified tender-round assignment is made. No later public SPPC renewable round than Round 7 or battery group than Group 2 was verified. This does not establish that private invitations or unindexed notices do not exist. Secondary Round 7 deadline reporting is not treated as a buyer-issued amendment.
- Price coverage and weighting: two slides display all 31 priced solar and seven priced wind projects as location points. The capacity-weighted average equals the sum of each project's capacity multiplied by its LCOE, divided by the sum of priced-project capacities. Solar: 53.70431 / 36.513 = 1.4708271027 US cents/kWh, displayed as 1.47. Wind: 11.833568 / 6.7 = 1.7662041791, displayed as 1.77. These are capacity-weighted averages, not medians. Provincial shading uses the same calculation within each province; it does not spatially interpolate tariffs. The three bands are below 1.50, 1.50 to below 2.00, and at least 2.00 US cents/kWh. Gray denotes no priced project. The calculation retains twelve full-precision SPPC awards and the unrounded KAPSARC API values for other projects; map labels are rounded only for display. Fifteen unpriced tenders are excluded from both numerator and denominator. Values are historical nominal generation benchmarks, not common-year tariffs, generation-weighted system costs or firm delivered electricity costs. One US cent/kWh equals USD 10/MWh.
- Renewable point locations: all 53 points come from the KAPSARC dashboard API checked on 11 September 2026. They are indicative project/locality positions, not surveyed plant coordinates. Number badges may be displaced with leader lines; the dots preserve the geographic anchors. Slide 4 combines the 15 tender points with province capacity shading. The 31 solar and seven wind price points appear on slides 7 and 8.
- Grid batteries: 21 distinct projects, totaling 42 GWh at cited project ratings: 18 GWh energized across nine Saudi Energy projects; 4 GWh in two further awarded SE sites, whose energization was not verified; 8 GWh under SPPC Group 1 agreements; 12 GWh in Group 2 procurement. Group 1 agreements were signed 20 August 2026; Group 2 qualifications were published 30 June 2026. Pipeline is not operating capacity.
- Fleet geography: SE's H1 2025 map provides eleven 2 GWh project ratings. Its H1 2026 release reports aggregate energized storage of 18 GWh after five projects added 10 GWh. NR Electric's Chinese release and the SE map identify Qaisumah; the supplier's English version inconsistently calls it Qassim. City/area proxies are not surveyed facility coordinates. SPPC projects use province-level maps.
- Off-grid project slide: slide 12 shows NEOM Green Hydrogen, The Red Sea and AMAALA, plus separately labeled ENOWA tenders at Shiqri and Gayal. NGHC uses one representative point; Red Sea and AMAALA use destination-area points; tender markers are named-area proxies. The first three systems total 4.49 GW. Adding the separately reported 0.8 GW Shiqri and 1.2 GW Gayal tenders gives 6.49 GW beyond the grid register. The 2024 bid reports do not establish current awards or grid-connection arrangements. Broader industrial research remains in the supporting register.
- The Red Sea: commercial operation announced 6 September 2026, 340 MWac solar and 1,227 MWh BESS. It is off-grid. Do not substitute a differently scoped 400 MW figure or count this as grid-fleet storage.
- AMAALA: RSG/Masdar give 250 MW solar and 700 MWh storage; EDF reports 770 MWh storage for the same utility system. The reviewed sources do not explain the boundary difference. It is not presented as a later increase or as two assets. Full utility COD was not established in this audit.
- NEOM / Oxagon: ACWA's current project sheet gives 3.9 GW renewable power, often rounded to 4 GW. NGHC reports 400 MW / 400 MWh BESS; Sungrow identifies 536 MW / 600 MWh on a DC supply basis for this same system. These are not added. First product is expected in 2027. NGHC commissioning milestones do not mean all nameplate capacity is operating.
- Yanbu: FEED covers 4 GW electrolysis and 400,000 t/year hydrogen, with a 2030 target. L&T's renewable/grid package concerns captive solar, wind, BESS, substations and transmission. The term "grid scope" does not confirm national-grid connection.
- ENOWA: 800 MW Shiqri solar and 1,200 MW Gayal wind have a separate 2024 reported tender history. A newer public award was not verified. NGHC also uses the name Shiqri; name matching alone would create a duplicate. NEOM/RCU supplier registration is not evidence of an open capacity-specific tender.
- Industrial capacity: Maaden Solar I is planned 1,500 MWth process heat for the Ras Al Khair alumina refinery. Its marker represents the industrial area in Eastern Province; the entire province is not presented as a project. The 2026 Al Khafji notice is technical support for an existing 10 MWdc solar plant. Aramco documents the 10.5 MW Al Midra solar carport in Dhahran and the 2.75 MW Turaif wind turbine commissioned in 2017. Their grid-connection configuration is not inferred. Aramco-associated national-grid joint ventures already present in the KAPSARC register are not counted again.
المصادر
يحتوي ملف PDF كذلك على صفحة مصادره الخاصة.
- Map-data license
- KAPSARC. Renewable Energy Projects Dashboard. July 2026 project snapshot
- SPPC / Principal Buyer. Renewable project register. 38 records checked 11 Sep 2026
- SPPC / Principal Buyer. Round 7: six projects, 5,300 MW. RFQ announcement, 16 Sep 2025
- SPPC / Principal Buyer. Round 7 qualified developers. Qualification notice
- SPPC / Principal Buyer. Round 6 awards and exact LCOEs. 27 Oct 2025
- SPPC / Principal Buyer. Seven PPAs totaling 15,000 MW. 13 Jul 2025
- Saudi Energy. H1 2026 earnings release, p. 4. 18 GWh energized; 17.8 GW renewables
- Saudi Energy. H1 2025 results presentation, p. 8. Fleet locations and project ratings
- NR Electric. 2.5 GW storage cluster energized. 27 May 2026 event; Chinese release
- HiTHIUM. Tabuk and Hail: 4 GWh contract. Company release, 27 Aug 2025
- SPPC / Principal Buyer. Group 1: four storage agreements. 20 Aug 2026
- Saudi Press Agency / SPPC. Group 2: all six project locations. 22 Apr 2026
- SPPC / Principal Buyer. Group 2 qualified applicants. 30 Jun 2026
- Acwa. The Red Sea: commercial operation. 6 Sep 2026; 340 MWac / 1,227 MWh
- Red Sea Global. AMAALA utility concession. 11 Sep 2023; 700 MWh design
- Masdar. Green Finance Report 2024, p. 14. 250 MW PV and 700 MWh storage
- EDF. 2025 registration document, p. 84. Filed Mar 2026; 770 MWh reported
- Acwa. NEOM Green Hydrogen project. Current project sheet; 3.9 GW power
- NEOM Green Hydrogen Co.. Project progress and milestones. Current page; first product in 2027
- Tecnicas Reunidas. Yanbu hydrogen FEED award. 26 Jul 2025; 4 GW electrolysis
- Larsen & Toubro. Yanbu renewables and grid scope. 22 Sep 2025; captive supply design
- GlassPoint. Maaden Solar I project. 1,500 MWth planned process heat
- MEED. ENOWA Gayal and Shiqri tenders. 24 Jul 2024; current award unverified
- NEOM. Official supplier portal. Tender invitations require selection
- Etimad. Al Khafji solar technical support. 2026 notice; 10 MWdc existing plant
- Royal Commission for AlUla. Official supplier portal. Procurement access; no capacity claim
- Italian Trade Agency / MEED. Round 7 deadline reporting. 19 Aug 2026; verify buyer addenda
- Sungrow. NGHC inverter and battery contract. 7 Aug 2023; 400 MWh / 600 MWh DC
- NEOM Green Hydrogen Co.. Battery system: 400 MW / 400 MWh. Official company post, 2026
- IRENA. Renewable capacity statistics 2026. 2024–2025 country totals; © IRENA 2026
- IEA. COP28 capacity pledge: 2025 update. p. 30: Saudi 20 GW/year and 130 GW ambition
- KAPSARC. Dashboard project coordinates and unrounded prices. Live API checked 11 Sep 2026; same 53-project snapshot
- Maaden. Solar steam showcase at Ras Al Khair alumina refinery. 11 Jan 2024; first stage of larger planned project
- Aramco. Renewables not that new. Al Midra, Dhahran: 10.5 MW solar carport
- Aramco. First wind turbine at Turaif Bulk Plant. 17 Jan 2017; 2.75 MW commissioned
- Bundesnetzagentur. Onshore wind auction statistics. Four 2025 rounds: 14,445.230 MW awarded
- Bundesnetzagentur. Ground-mounted solar auction statistics. Three 2025 rounds: 7,250.630 MW awarded
- UK Department for Energy Security and Net Zero. Allocation Round 7 completed results. 10 Feb 2026; 14.7 GW across AR7 and AR7a
- China NDRC / NEA. Renewable electricity pricing reform, Notice 136. 9 Feb 2025; provincial energy-volume settlement auctions
- Global Energy Monitor. Solar and wind project location records. NGHC and AMAALA coordinate references; per-project URLs in coordinate register
- GeoNames. Geographic place gazetteer. Named-area proxies for Ras Al Khair and Shiqri; CC BY 4.0
- Electronics / MDPI. A Case Study of a Stand-Alone AC and DC Power Network in the Red Sea New City. 2026, 15(5), 1077; destination coordinate only
- DistancesFrom. Al Midra Tower coordinates. Building-area proxy, not surveyed solar-panel footprint
- The Wind Power. Turaif oil storage depot wind turbine. Location record, 20 May 2026
- Saudi Energy / Saudi Exchange. Al-Muwaih storage services agreement. 23 Aug 2026; contract value SAR 1.06 billion
- Saudi Energy / Saudi Exchange. Haden storage services agreement. 23 Aug 2026; contract value SAR 1.08 billion
- Saudi Energy / Saudi Exchange. Kahafah storage services agreement. 23 Aug 2026; contract value SAR 1.11 billion
- Ember. How cheap is battery storage?. 11 Dec 2025; pp. 6 and 10–12; Oct 2025 evidence
- SaudiGulf Projects. SEC receives bids for 1,000 MW battery storage. 22 Apr 2025; lowest submitted supply and construction prices
معاينة
الصفحات المعروضة: 3 من 15
الحصول على التقرير
الطاقة المتجددة وتخزين البطاريات في المملكة: الدليل الكامل
احصل على ملف PDF مجانًا مع العضوية
ملف PDF وملفات البيانات متاحة مجانًا للأعضاء. تستغرق العضوية دقيقة: تحقّق من بريد إلكتروني أو رقم جوال مرة واحدة، ليُفتح التنزيل مع لوحات البيانات وتصدير CSV.
أنشئ حسابًا مجانيًا ويبدأ التنزيل فور دخولك، ثم تعود إلى هذا التقرير.
لست مستعدًا للانضمام بعد؟
الموجز الأسبوعي
الطاقة المتجددة في المملكة أسبوعيًا: تغيّرات مراحل المشاريع والمناقصات ومواعيد التشغيل التجاري. رسالة واحدة يوم الأحد.
إذا تابعت بأحد هذه الحسابات، فأنت توافق على شروط الاستخدام، بما فيها الترخيص وأحكام العضوية، وعلى سياسة الخصوصية.
نستخدم بياناتك لنتيح لك الوصول، ولنرسل إليك الموجز الأسبوعي أو التنبيهات التي تختارها إن طلبت ذلك. سياسة الخصوصية
الأرقام كما صدرت في 12 سبتمبر 2026؛ وقد تختلف لوحات البيانات الحية. افتح لوحة البيانات الحية